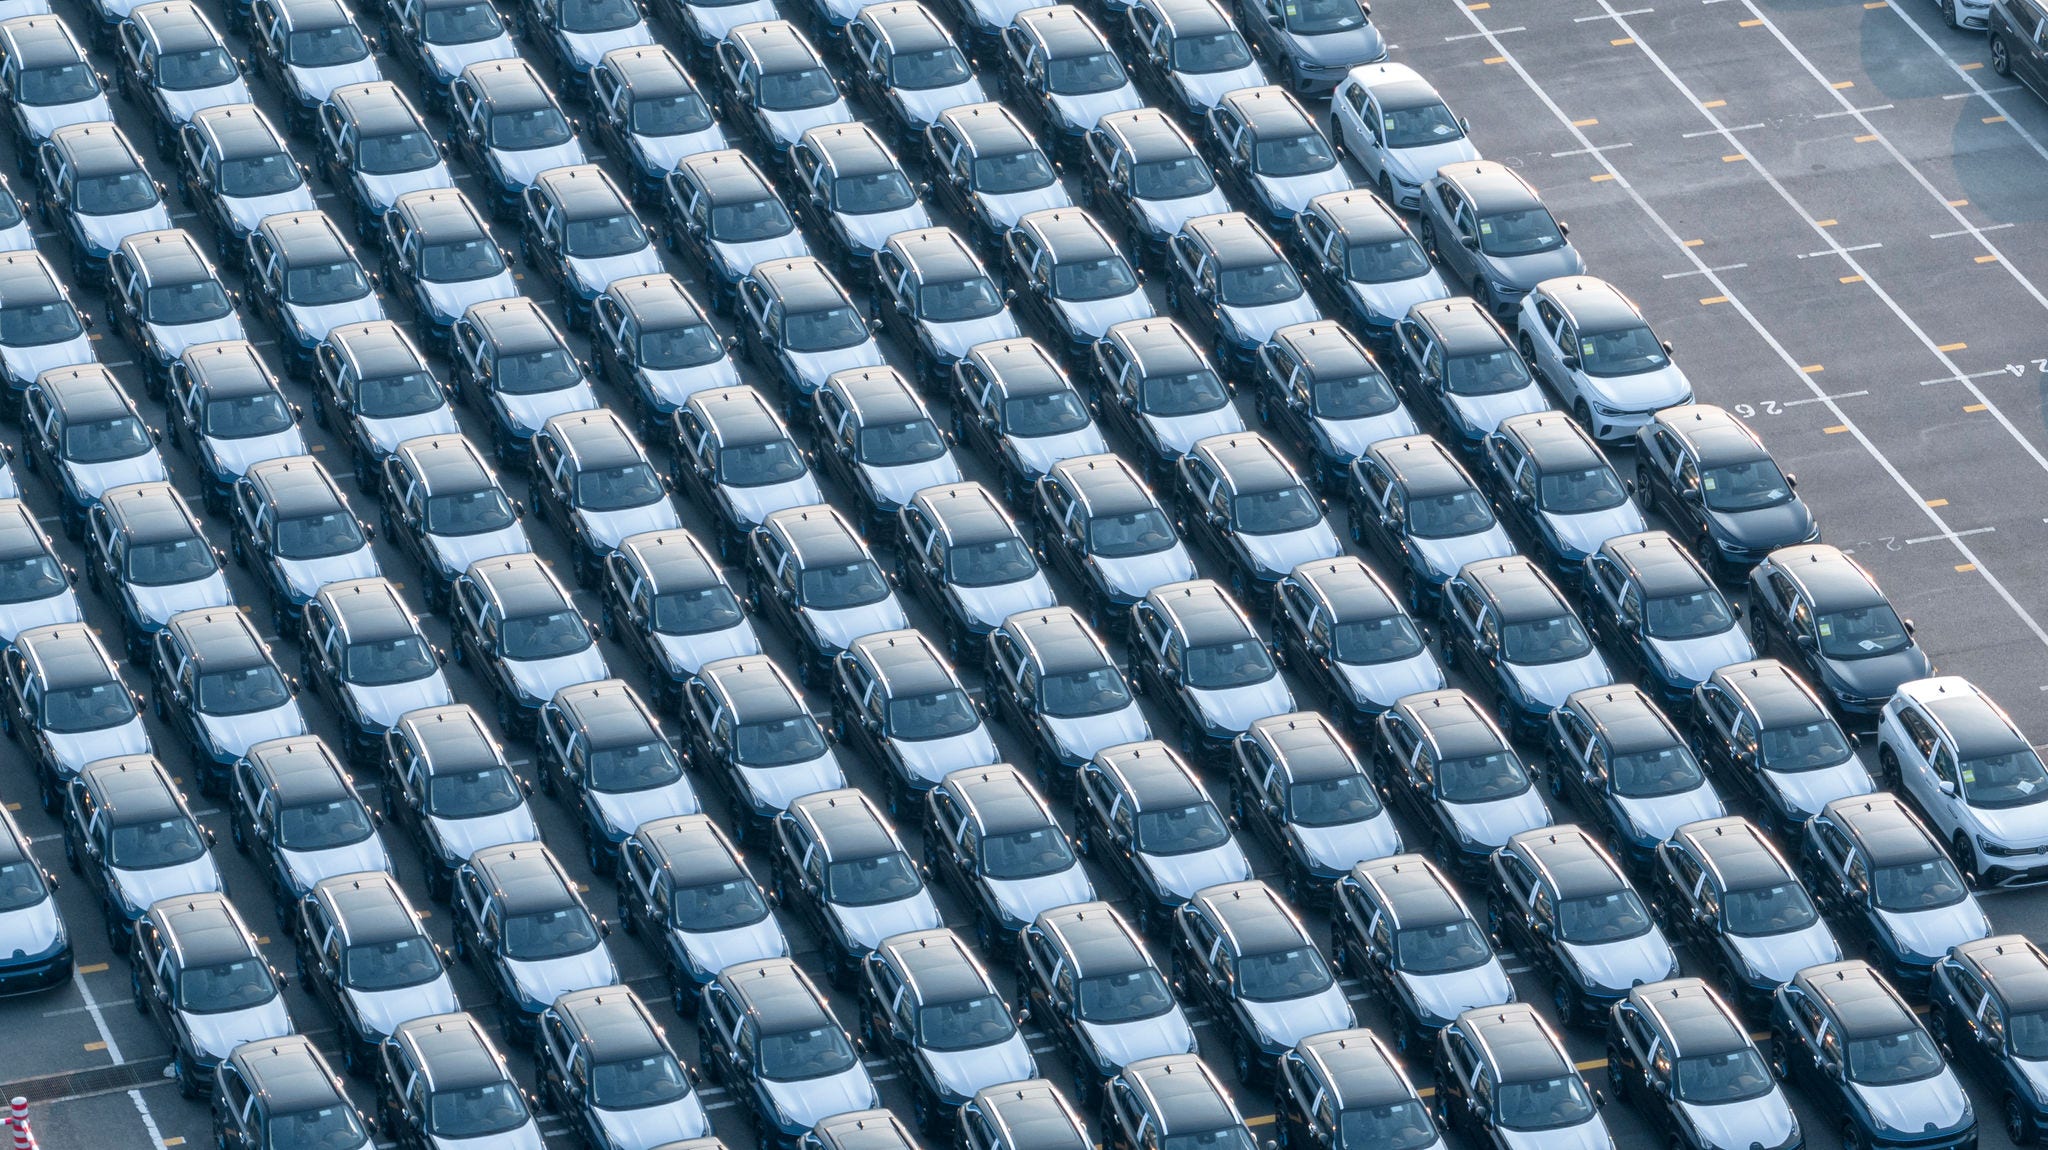
What is China selling to the world? Seemingly everything.
Decades ago, China was known for producing low-value-added products like apparel and stuffed animals. But those days are in the distant past: In 2026, China will export over $300 billion worth of semiconductors and microassemblies as well as approximately $400 billion worth of lithium-ion batteries, motor vehicles, and auto parts.
China’s growing dominance in global supply chains is evident in its trade surplus, which reached $1.2 trillion in 2025—a 1,055% increase over the last 20 years (Exhibit 1). Last week, China reported a new monthly record trade surplus of $133.5 billion on the back of a 36.3% year-on-year (y-o-y) surge in exports to $447.2 billion, as well as a 31% y-o-y increase in imports to $313.7 billion as the country becomes ever more integrated into the global supply chain.
EXHIBIT 1
China’s 2026 Trade Surplus Is Likely to Top $1.2 Trillion
China’s Trade Surplus/Deficit with Key Trading Partners
As of September 2026
Source: Lazard, Bloomberg, China Customs General Administration. China’s trade surpluses are plotted above zero with its deficits below. The black line shows the total trade surplus. Estimate for 2026 is based on seasonally adjusted annualized data through September.
China has benefited from an incredibly successful set of mercantilist industrial policies since joining the World Trade Organization as an emerging economy in 2001, and since then it has built world-leading companies that are increasingly ravaging the industrial bases of developed and emerging economies.
In 2025, over 75% of the countries that traded with China found themselves in a trade deficit. The lucky few countries that generated trade surpluses were generally those selling commodities (e.g., Brazil and Australia) or critical technology inputs like semiconductors (e.g., Taiwan and South Korea).
Amber lights had been flashing in global capitals for years, but now those lights are turning red—and this is not only true in the United States. In the first nine months of 2026, for example, the European Union trade deficit increased 26% from the prior year-to-date (YTD) period with monthly deficits exceeding $30 billion in each of the last six months. The EU deficit now exceeds the US deficit by nearly 19% despite EU GDP being about 40% smaller than that of the United States.
Even India, a nation with significant labor cost advantages relative to China, is burdened with a $106 billion trade deficit YTD (versus $88 billion in the same period in 2025), meaning India’s deficit is 45% of the size of the US deficit even while Indian GDP is 87% smaller.
China’s one surprisingly small export is for rare earths at only $3.4 billion YTD. But the relatively small dollar value of rare earths exports is misleading given the array of manufacturing supply chains that rely on China as the dominant supplier of these inputs. And if China’s ability to limit access to a product that represents only ~0.1% of its exports can cause such consternation in global capitals, how many other chokepoints must be within China’s grasp?
The challenge for trading partners globally is that, over time, as China wins more market share, it tends to drive overseas competitors out of business. Once a chokepoint becomes evident, it could take years for a trade counterpart to rebuild its indigenous production capability if that is even possible.
The European Union is belatedly getting serious about protecting its domestic industries, but the United States has been less aggressive since China demonstrated escalation dominance in 2025 by shutting off access to critical minerals and rare earths.
At some point, I believe the developed world will be forced to act in unison or face a dangerous dependency on a country that has demonstrated a willingness to capitalize on its supply chain dominance—as it did with critical minerals and rare earths.
China, on the other hand, must also recognize that its dependency on exports is unsustainable. As I argued in my mid-year outlook, China needs to address its domestic weaknesses to set the stage for sustained growth. Absent this rebalancing, the risk to global growth will continue to grow.
Important Information
Published on 21 October 2026.
This content represents the views of the author(s), and its conclusions may vary from those held elsewhere within Lazard.
These materials have been prepared by Lazard for general informational purposes only on a nonreliance basis and they are not intended to be, and should not be construed as, financial, legal, or other advice.
In preparing these materials, Lazard has assumed and relied upon the accuracy and completeness of any publicly available information and of any other information made available to Lazard by any third parties, and Lazard has not assumed any responsibility for any independent verification of any of such information.
These materials are based upon economic, monetary, market and other conditions as in effect on, and the information available to Lazard as of, the date hereof, unless indicated otherwise. Subsequent developments may affect the information set out in this document and Lazard assumes no responsibility for updating or revising these materials.
These materials may include certain statements regarding future conditions and events. These statements and the conditions and events they describe are inherently subject to uncertainty, and there can be no assurance that any of the future conditions or events described in these materials will be realized. In fact, actual future conditions and events may differ materially from what is described in these materials. Lazard assumes no responsibility for the realization (or lack of realization) of any future conditions or events described in these materials.
No liability whatsoever is accepted and no representation, warranty or undertaking, express or implied, is or will be made by Lazard or any of its affiliates for any information contained herein or for any errors, omissions, or misstatements herein. Neither Lazard nor any of its affiliates makes or has authorized to be made any representations or warranties (express or implied) in relation to the matters contained herein or as to the truth, accuracy, or completeness of this document.
Nothing herein shall constitute a commitment or undertaking on the part of Lazard to provide any service. Lazard shall have no duties or obligations to you in respect of these materials or other advice provided to you, except to the extent specifically set forth in an engagement or other written agreement, if any, that is entered into by Lazard and you.
By accepting this document each recipient agrees to be expressly bound by the foregoing limitations.